


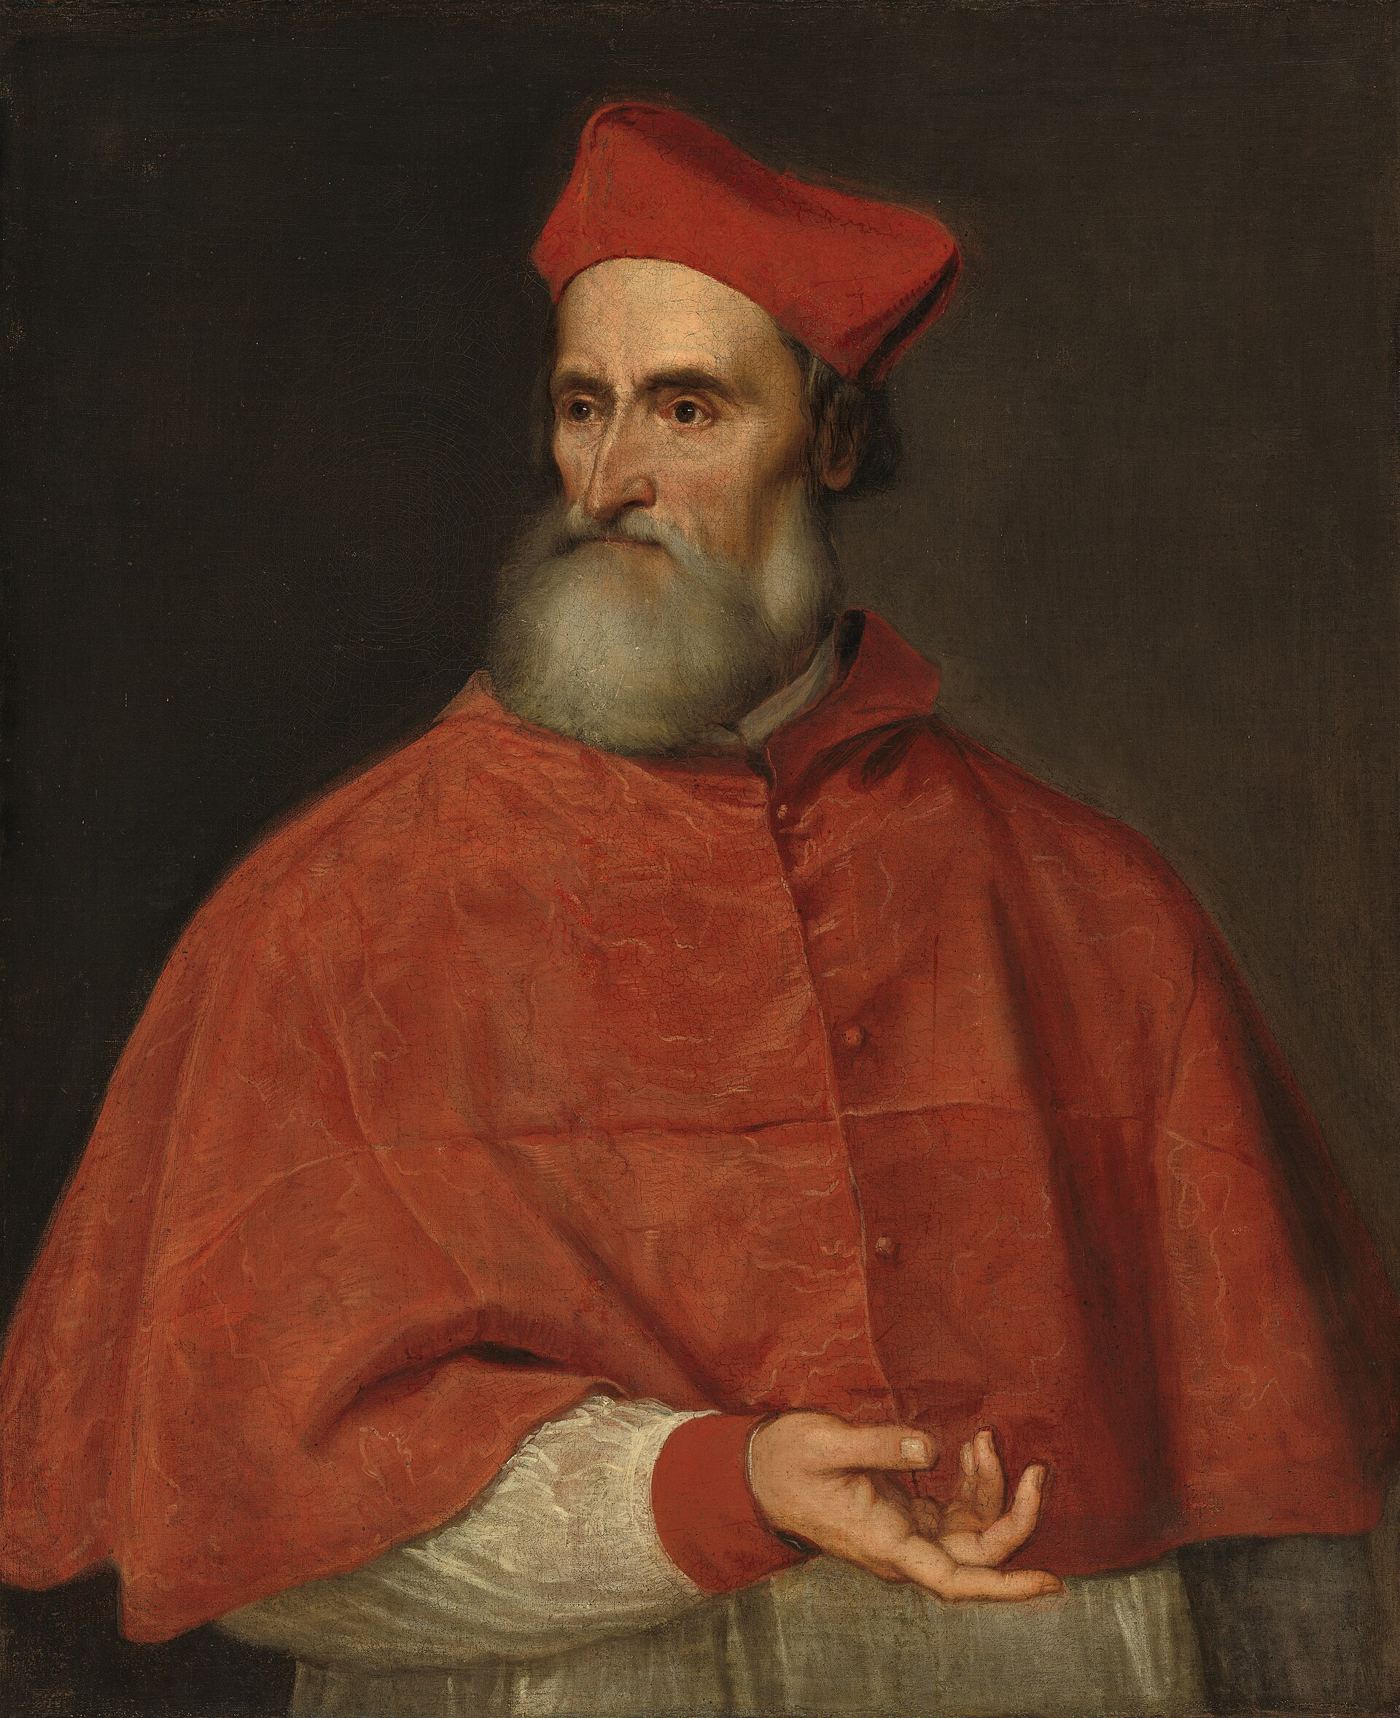
The gavel numbers from Paris Art Week and the London auctions made the usual noise: multi-million results, records for rediscovered names, a masterpiece changing hands for the price of a small airline. Yet beneath the headline lots, the art market’s structure is shifting in ways the record prices conceal — a thinner middle, a younger and more global buyer base, and a growing share of value moving in private sales nobody headlines at all.
Top-end strength alongside mid-market softness is the signature of a wealth-concentrated economy, and art has become one of its most legible dials. The very rich, diversified across everything else, buy scarcity and story; the merely affluent, squeezed by rates and caution, sit out the middle lots. Our culture and business pages read the season’s results as economic data wearing evening dress.
What the New Buyers Want
Younger collectors — now a decisive share of high-end bidding — buy differently: across categories, on phones, with research habits borrowed from markets, and with a pronounced interest in artists the canon undervalued, whose prices are consequently being rewritten in real time. Women artists and artists from the global south have set many of the season’s records, part correction, part speculation, wholly overdue.
The fair-and-auction calendar has also rebalanced geographically — Paris’s post-Brexit ascendancy over London being the subplot every result feeds, alongside growing seasons in Seoul, Hong Kong and the Gulf.
Art as Asset, With Caveats
Advisers now package art within wealth management as fluently as wine or watches, complete with lending against collections. The Art Basel and UBS market reports document the financialisation in detail. The records, then, are real but partial evidence: of a market where the top is a vault, the middle is a question, and the story is never only about the pictures.
The geography subplot has its own momentum. Paris’s rise was engineered — auction houses invested, fairs relocated, and post-Brexit trade friction did the rest — while London’s depth of expertise keeps it a co-capital rather than a dethroned one. The more interesting migration is digital and generational at once: a rising share of high-value bidding now happens on phones, by collectors who may never attend a sale room, which shifts the theatre of the market from the rostrum to the alert. Specialists call it the market’s streaming era — global, continuous, less ceremonial and harder to read, because the private treaty sale, concluded by message, leaves no gavel to report. The record prices will keep coming; they are the market’s advertising. The market itself increasingly happens offstage.
For the merely curious, the season’s most honest exhibit may be the free one: the pre-sale viewings, where the public can stand in front of the masterpieces before they vanish into the vaults their prices describe. The market’s theatre is gilded, contested and — for those few days — open to everyone.
